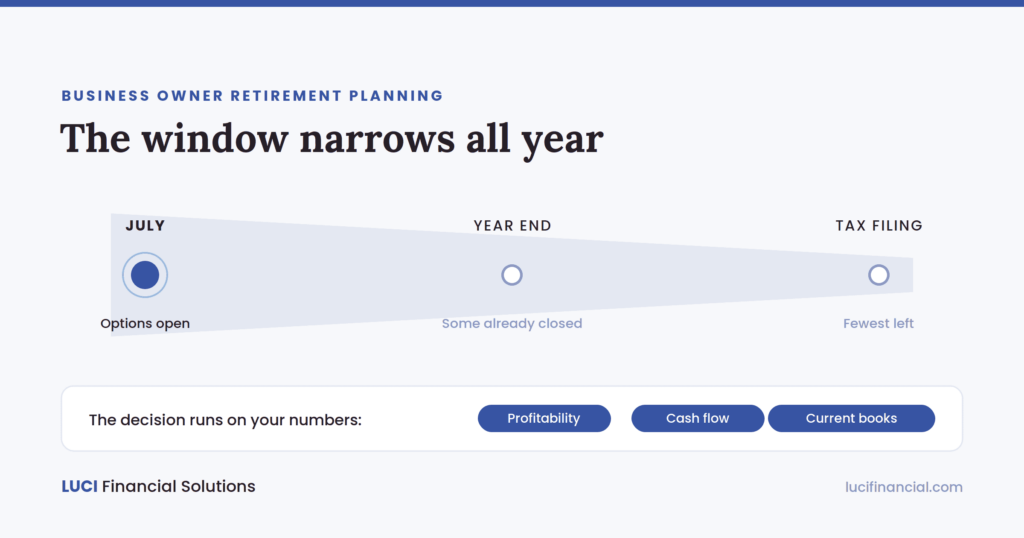
Short answer: July is the right time for business owner retirement planning because some plans close months before December: most existing businesses must set up a new SIMPLE IRA by October 1. The choice depends on profit, cash flow, payroll and structure, so a Dallas owner needs current, reviewed books by mid-year to give a CPA and financial advisor real numbers instead of guesses.
Key takeaways
- Setting up a plan and funding it often have two different deadlines.
- A new SIMPLE IRA must be set up by October 1 for most existing businesses (IRS).
- A SEP can be set up and funded until the business return’s due date, including extensions (IRS).
- Your CPA projects the tax effect and your advisor compares plans; both need current books.
- Books three months behind in July mean guessing at a decision that costs real money.
Why July, not December
Every July, I watch business owners make the same quiet decision: retirement planning can wait until December. It feels reasonable. The year is only half over, and there are more urgent fires to put out.
My colleague Tonyia Cleaver, a Wealth Advisor and Strategist, explains below why that instinct is expensive. Some business owners’ retirement planning decisions have to be made well before year-end, and by the time most owners start thinking about it, certain options are already off the table.
But here is the part that sits squarely in my lane. Look at what the plan decision actually depends on: profitability, cash flow, business structure, and what you can realistically commit to funding. Every one of those is a question your financials answer. If your books are three months behind, you are not choosing a retirement plan. You are guessing at one. Here is Tonyia’s breakdown of the options and the deadlines that matter.
The Calendar Matters More Than Most Business Owners Realize
By Tonyia Cleaver, CEPA® Wealth Advisor and Strategist
As we begin the second half of the year, many business owners are taking inventory of what they have accomplished and what still needs their attention. If establishing a retirement plan for your business is still on your to do list, now is the time to move it to the top.
One of the biggest misconceptions I see is that retirement planning can wait until December. While there is still time to take advantage of many retirement planning opportunities for 2026, several plans have deadlines for when they must be established, while others have different deadlines for making contributions.
Understanding those deadlines now can help you avoid missing valuable tax planning opportunities later.
It is also important to remember that establishing a retirement plan and funding a retirement plan are often two different deadlines. Some plans must be in place before the end of the year, or even earlier, while others allow contributions up to your tax filing deadline.
Because every business is different, planning ahead creates more options.
The most effective planning happens when your CPA and financial advisor work together. Your CPA can project the tax impact based on your current financial results, while your financial advisor can help evaluate the retirement plan options that best fit your business, cash flow, and long term goals. Together, those conversations help you make informed decisions instead of rushed ones.
A common question I hear is: which retirement plan is best?
The answer depends on several factors, including your business structure, profitability, number of employees, cash flow, and personal retirement objectives. The best retirement plan is not necessarily the one with the highest contribution limit. It is the one that supports your business today while helping you build the future you want tomorrow.
Below is a high-level overview of some of the most common retirement plan options available to business owners.
Retirement Plan Options and Key Deadlines
| Retirement Plan | Establish By | Contribution Deadline | Best For |
|---|---|---|---|
| Solo 401(k) | Generally before year end* | Business tax filing deadline (employer contributions may generally be made by filing deadline, including extensions); employee contributions are due by year end | Self-employed individuals or businesses with no eligible employees |
| SIMPLE IRA | October 1 for most existing businesses establishing a new plan | Per plan requirements | Small businesses with employees |
| SEP IRA | Tax filing deadline, including extensions | Tax filing deadline, including extensions | Flexible employer contributions |
| Traditional IRA | Tax filing deadline | Tax filing deadline | Eligible individuals |
| Roth IRA | Tax filing deadline | Tax filing deadline | Eligible individuals (income limits apply) |
*Rules and deadlines can vary based on your business structure and current IRS guidance.
How to read this table: read the “Establish by” column first. It is the one that closes doors: a SIMPLE IRA has to be set up by October 1 for most existing businesses, while a SEP can still be opened until the business tax filing deadline, including extensions. The contribution column tells you how long you have to fund the plan once it exists. (Note added by LaTara Scott.)
Planning ahead allows more time to evaluate your options rather than making decisions under pressure.
If opening a retirement plan has been on your list this year, now is an excellent time to begin the conversation with your CPA and financial advisor.
About the Author
Tonyia Cleaver, CEPA®, is a Wealth Advisor and Strategist who helps business owners, individuals, and families make intentional financial decisions that align with their goals, values, and life’s transitions. She specializes in retirement planning, business owner strategies, and helping clients navigate life’s major transitions.
Tonyia can be reached at 908-955-0077 x315 or tonyia@wwbpartners.com.
What your books need to show before you pick a plan
Tonyia made a point worth repeating: the best planning happens when your advisors work together. Your financial advisor evaluates the plan options. Your CPA projects the tax impact. Both of them are working from the same source: your financial statements. If your numbers are current and accurate, those conversations take one meeting. If they are not, the conversation stalls while everyone waits for the books to catch up.
| Question your advisors will ask | Where the answer comes from | What makes it reliable |
|---|---|---|
| How profitable is the business this year? | Year-to-date Profit & Loss and a full-year projection | Every account reconciled through the latest month |
| How much can you commit to funding? | Statement of Cash Flows and a cash forecast | Owner draws and loan payments recorded separately |
| Who would be eligible employees? | Payroll reports by employee | Payroll entries that match the payroll provider |
| What is the business structure? | Entity records and the tax return type | Owner pay recorded the way the structure requires |
| What changed since last year? | Profit & Loss compared with the same period last year | The same categories used both years |
How to read this table: each row is a question your CPA or advisor will ask in the first meeting. If you cannot produce the report in the middle column today, or you are not sure it is right, that is the work to finish before the meeting, not after it.
A retirement-plan calendar for Dallas business owners
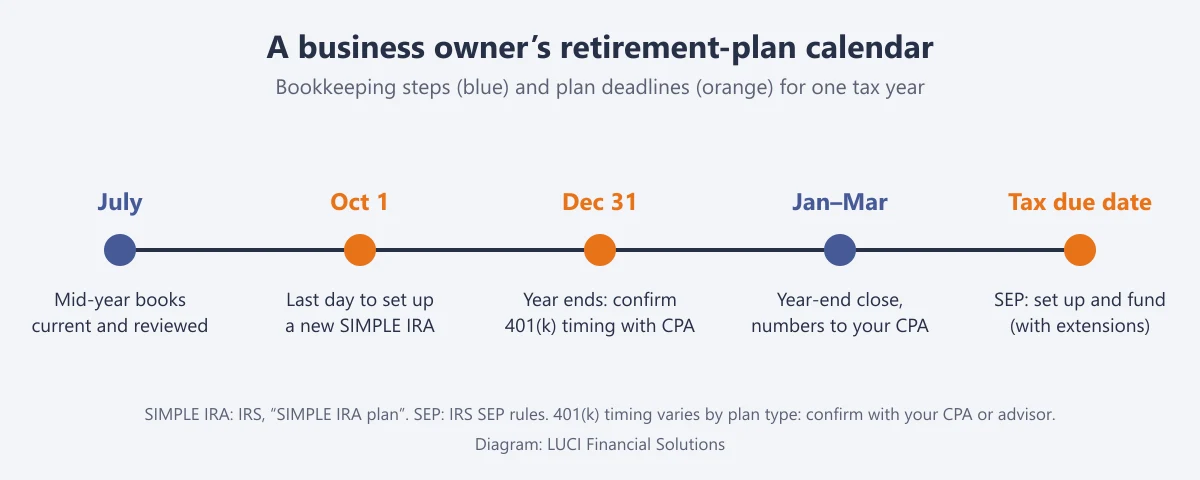
- July: bring the books current through June and have them reviewed. Book the CPA and advisor conversations.
- August and September: compare plan options with a projection of the full year. If a SIMPLE IRA is the choice, set it up before October 1.
- October to December: keep the monthly close on schedule so the year-end projection stays accurate; confirm any 401(k) timing with your CPA.
- January to March: close the year, deliver the year-end package to your CPA and fund contributions due with the return.
- By the tax filing deadline: a SEP can still be set up and funded, including extensions.
Reading this after October? What may still be open
If the SIMPLE IRA date has passed, the year is not lost. A SEP can be established and funded up to the business tax filing deadline, including extensions, and individual IRA contributions follow the individual filing deadline. Rules for 401(k) plans depend on the plan type and whether it is the plan’s first year, so ask your CPA early in December rather than in March. In every case, the conversation goes faster with books that are current through the latest month.
For the bookkeeping side of year-end, our year-end bookkeeping checklist for Dallas businesses lists what to close out before January, and the monthly reports your bookkeeper should send covers the statements your advisors will ask for.
Your books should be ready before the deadline is
If you want to talk with Tonyia about which plan fits your situation, her information is above. If you are not confident that your financial statements and bookkeeping could support that conversation today, that is the conversation to have with us first.
LUCI Financial Solutions provides fractional financial operations, including bookkeeping, controller, and CFO advisory, for businesses across the Dallas–Fort Worth area and nationwide. Every client starts with monthly bookkeeping, reconciliations and a senior review, a monthly reporting package and a year-end package for the tax preparer. LUCI does not select retirement plans or give investment advice; we make sure the numbers your CPA and advisor use are right. Questions about what we do are answered in our financial operations FAQs.
Frequently asked questions about business owner retirement planning
When should a business owner start retirement planning for the year?
By mid-year. Some plans must be set up months before December, such as a SIMPLE IRA, which most existing businesses must establish by October 1. Starting in July leaves time to review the numbers with your CPA and advisor before those dates.
What is the deadline to set up a SIMPLE IRA?
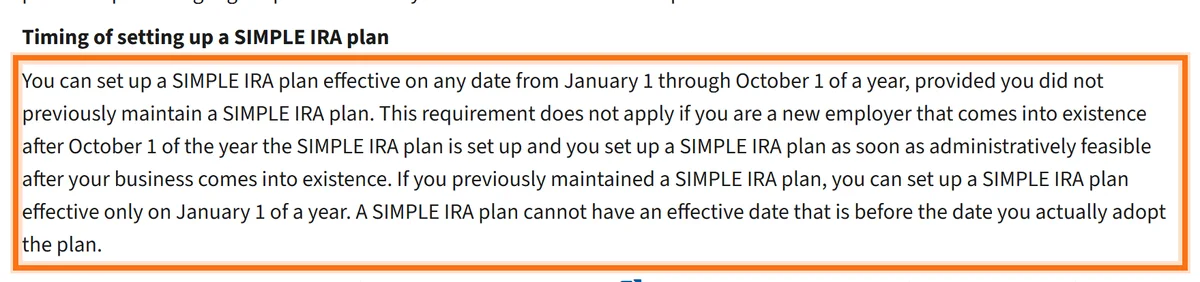
The IRS allows a SIMPLE IRA to be set up effective any date from January 1 through October 1 of a year if you have not had one before. A new business that starts after October 1 can set one up as soon as administratively feasible.
Can I still open a SEP after December 31?
Yes. The IRS allows a SEP to be established and funded as late as the due date of the business income tax return for that year, including extensions.
What financial information do I need before choosing a retirement plan?
Current, reconciled books: a year-to-date Profit & Loss, a projection of the full year, payroll by employee, cash on hand and expected cash needs, and the business structure. Your CPA uses these to estimate the tax effect and your advisor to compare plans.
Does LUCI Financial Solutions choose my retirement plan?
No. LUCI keeps the books and prepares the financial statements; plan selection belongs with your financial advisor and the tax projection with your CPA. We make sure the numbers they work from are current and reviewed.
Does LUCI help Dallas business owners get their books ready for year-end?
Yes. LUCI keeps the books for established Dallas–Fort Worth businesses every month with a senior review, sends a monthly reporting package, and prepares a year-end financial package for your tax preparer.
Retirement-ready numbers
Current, reviewed books and a year-end package your CPA can use. Schedule a conversation with LaTara Scott or see our bookkeeping services in Dallas.